
Understanding Mortgage Debt and the Need for Help
Mortgage debt can be a significant burden for many homeowners. Missing payments, facing foreclosure, or simply struggling to keep up with monthly dues can create immense stress and financial instability. When you find yourself in this situation, exploring available resources is crucial. One option to consider is credit counseling specifically tailored for mortgage debt.
What is Credit Counseling for Mortgage Debt?
Credit counseling for mortgage debt involves working with a certified credit counselor who specializes in housing and mortgage-related issues. These counselors are trained to assess your financial situation, understand the complexities of your mortgage, and help you develop a plan to address your debt.
How Credit Counseling Works
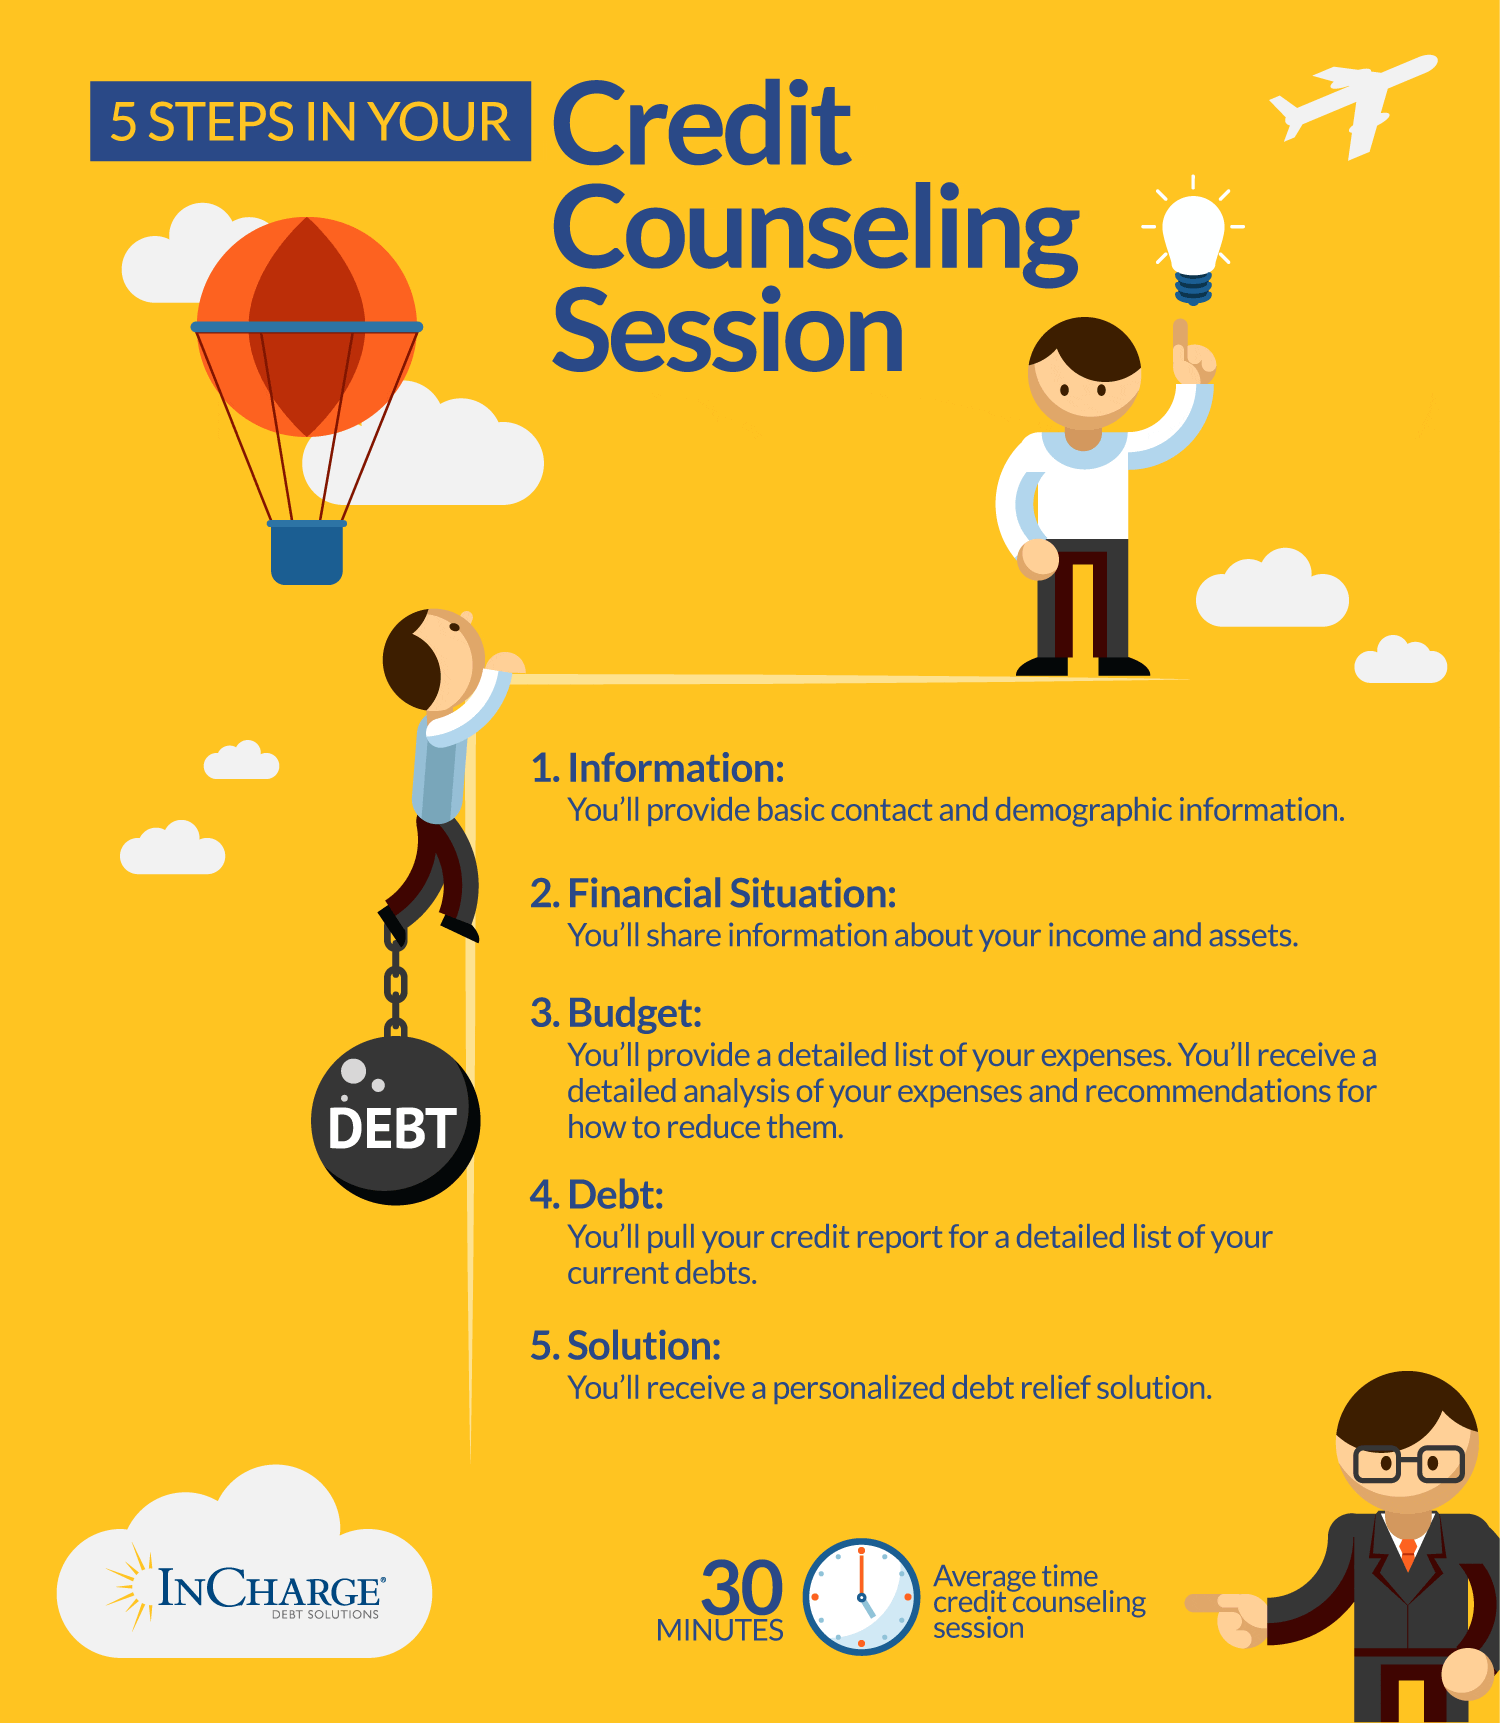
The process typically involves several key steps:
Initial Consultation and Assessment
During the initial consultation, the credit counselor will gather information about your income, expenses, assets, and debts, including your mortgage. They will review your credit report to understand your overall financial health and identify any potential issues. This comprehensive assessment allows the counselor to gain a clear picture of your situation and determine the best course of action.
Budget Analysis and Financial Planning
The counselor will help you create a realistic budget that prioritizes your essential expenses, including your mortgage payment. They will analyze your spending habits and identify areas where you can cut back to free up funds for debt repayment. This budgeting process is crucial for regaining control of your finances and preventing further debt accumulation.
Mortgage Review and Options Evaluation
The credit counselor will carefully review your mortgage terms, including the interest rate, loan type, and payment schedule. They will explore various options for managing your mortgage debt, such as:
- Negotiating with your lender: Counselors can act as intermediaries between you and your lender to negotiate more favorable terms, such as a lower interest rate, a modified payment plan, or a forbearance agreement.
- Mortgage modification: This involves permanently changing the terms of your mortgage to make it more affordable. Modifications can include reducing the interest rate, extending the loan term, or adding missed payments to the loan balance.
- Refinancing: Refinancing involves taking out a new mortgage to pay off your existing one. This can be beneficial if you can secure a lower interest rate or a more favorable loan term.
- Government assistance programs: Counselors can help you identify and apply for government programs that offer financial assistance to homeowners struggling with their mortgage payments. Examples include programs offered by the Department of Housing and Urban Development (HUD).
Debt Management Plan (DMP)
While a DMP is more commonly associated with unsecured debts like credit cards, a counselor may incorporate elements of it into your overall plan for managing your mortgage debt. This could involve prioritizing your mortgage payment and making sure it's paid on time each month, while also addressing other debts that may be contributing to your financial strain.
Benefits of Credit Counseling for Mortgage Debt
There are several potential benefits to seeking credit counseling for mortgage debt:
Expert Guidance and Support
Certified credit counselors have extensive knowledge of mortgage debt and the available options for managing it. They can provide expert guidance and support throughout the process, helping you make informed decisions and navigate the complexities of the mortgage industry.
Negotiation Skills
Credit counselors are skilled negotiators who can advocate on your behalf with your lender. They can often secure more favorable terms than you might be able to obtain on your own.
Improved Financial Literacy
Credit counseling can help you improve your financial literacy and develop better money management skills. This can empower you to take control of your finances and avoid future debt problems.
Reduced Stress and Anxiety
Dealing with mortgage debt can be incredibly stressful. Credit counseling can provide you with a sense of hope and direction, reducing your stress and anxiety.
Foreclosure Prevention
One of the primary goals of credit counseling for mortgage debt is to help you avoid foreclosure. By working with a counselor, you can explore options for keeping your home and getting back on track with your mortgage payments.
Choosing the Right Credit Counseling Agency
It's crucial to choose a reputable and certified credit counseling agency. Look for agencies that are:
Accredited by a Reputable Organization
Ensure the agency is accredited by an organization like the National Foundation for Credit Counseling (NFCC) or the Financial Counseling Association of America (FCAA). Accreditation indicates that the agency meets certain standards of quality and professionalism.
Nonprofit
Nonprofit credit counseling agencies are generally more focused on helping consumers than making a profit. They typically offer lower fees and more unbiased advice.
HUD-Approved
If you're seeking assistance with a government-backed mortgage, consider working with a HUD-approved housing counseling agency. These agencies have specific expertise in helping homeowners navigate government programs and resources.
Transparent Fees
The agency should be transparent about its fees and services. Be wary of agencies that charge high upfront fees or make unrealistic promises.
When is Credit Counseling Right for You?
Credit counseling can be a valuable resource for homeowners who are:
Struggling to Make Mortgage Payments
If you're consistently behind on your mortgage payments or are at risk of falling behind, credit counseling can help you explore options for getting back on track.
Facing Foreclosure
If you've received a foreclosure notice, it's essential to seek help immediately. A credit counselor can help you understand your rights and explore options for avoiding foreclosure.
Overwhelmed by Debt
If you're feeling overwhelmed by your overall debt burden, including your mortgage, credit counseling can help you develop a plan to manage your finances and reduce your debt.
Unsure of Their Options
If you're unsure of what options are available to you for managing your mortgage debt, a credit counselor can provide you with the information and guidance you need to make informed decisions.
Alternatives to Credit Counseling
While credit counseling can be beneficial, it's not the only option for managing mortgage debt. Other alternatives include:
Direct Negotiation with Your Lender
You can try negotiating directly with your lender to modify your mortgage terms or arrange a payment plan.
Debt Settlement
Debt settlement involves negotiating with your creditors to pay less than the full amount you owe. However, this can have negative consequences for your credit score.
Bankruptcy
Bankruptcy is a legal process that can discharge some or all of your debts. However, it can have a significant impact on your credit score and financial future.
Finding a Credit Counseling Agency
You can find a credit counseling agency through:
- The National Foundation for Credit Counseling (NFCC): nfcc.org
- The Financial Counseling Association of America (FCAA): fcaa.org
- The U.S. Department of Housing and Urban Development (HUD): hud.gov
Remember to carefully research any agency before enlisting their services to ensure they are reputable and qualified to help you with your specific situation. Seeking professional help can be a crucial step towards regaining financial stability and protecting your home.

0 Comments