
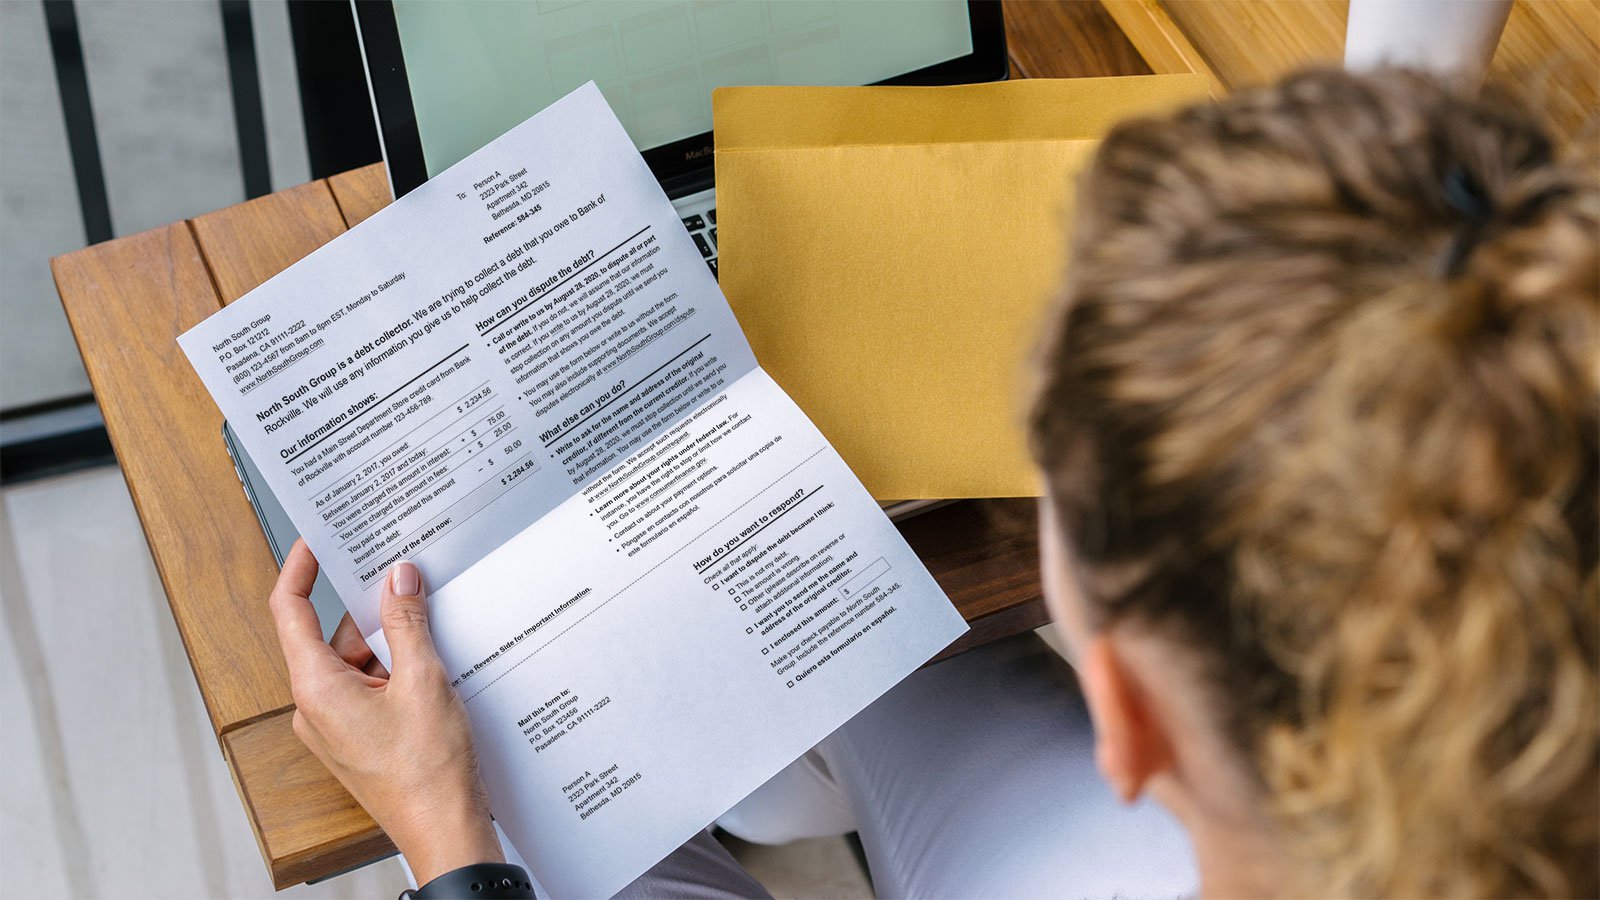
Understanding Debt Collectors and Your Rights
Dealing with debt collectors can be a stressful and overwhelming experience. It's crucial to understand who they are, how they operate, and most importantly, your rights. Debt collectors are businesses that attempt to recover debts owed to other companies or individuals. These debts can range from unpaid credit card balances to medical bills and everything in between. Knowing your rights is your first line of defense when facing debt collection agencies.
Who are Debt Collectors?
Debt collectors aren't always the original creditor. Often, they are third-party agencies that purchase debts for pennies on the dollar. This means they buy the right to collect the debt, not necessarily that they have all the original documentation or proof of the debt's validity. Understanding this distinction is essential because it impacts how you should respond to them.
Your Rights Under the Fair Debt Collection Practices Act (FDCPA)
The Fair Debt Collection Practices Act (FDCPA) is a federal law that protects consumers from abusive, unfair, and deceptive debt collection practices. Some key rights under the FDCPA include:
- Right to Validation: You have the right to request validation of the debt. This means the debt collector must provide proof that you owe the money, including the original creditor's name, the amount of the debt, and an explanation of how the debt was incurred.
- Right to Cease Communication: You can send a written request to the debt collector to stop contacting you. Once they receive this request, they can only contact you to confirm they will no longer contact you or to inform you that they intend to take legal action.
- Protection from Harassment: Debt collectors are prohibited from harassing, oppressing, or abusing you. This includes calling you repeatedly, using obscene language, or threatening you with actions they cannot legally take.
- Restrictions on Contact Times: Debt collectors cannot contact you before 8:00 a.m. or after 9:00 p.m. without your permission.
- Prohibition of False or Misleading Representations: Debt collectors cannot lie or make false claims about the debt or their authority.
Strategies to Avoid Debt Collectors
While understanding your rights is crucial, proactively managing your finances and addressing debt can significantly reduce the likelihood of dealing with debt collectors in the first place. Here are some strategies to help you avoid debt collectors:
1. Create a Budget and Stick to It
Budgeting is the cornerstone of financial stability. By tracking your income and expenses, you can identify areas where you can cut back and allocate more funds towards debt repayment. There are many budgeting apps and tools available that can help you automate this process and stay on track. A well-crafted budget allows you to prioritize essential expenses and avoid overspending, which can lead to accumulating debt.
2. Prioritize Debt Repayment
If you already have debt, prioritize paying it down aggressively. Consider using strategies like the debt snowball method (paying off the smallest debts first for psychological wins) or the debt avalanche method (paying off the highest-interest debts first to save money in the long run). Even small extra payments can make a significant difference over time.
3. Negotiate with Creditors
Don't be afraid to negotiate with your creditors. They may be willing to offer a lower interest rate, a payment plan, or even a partial debt forgiveness. Contact your creditors and explain your situation. Be honest about your financial difficulties and demonstrate your willingness to work towards a solution. Many creditors prefer to negotiate rather than risk not receiving any payment at all.
4. Explore Debt Consolidation Options
Debt consolidation involves taking out a new loan to pay off multiple existing debts. This can simplify your finances by combining multiple payments into one, and it may also result in a lower interest rate. Options for debt consolidation include:
- Personal Loans: Unsecured personal loans can be used to consolidate debt.
- Balance Transfer Credit Cards: These cards offer low or zero percent introductory interest rates, allowing you to transfer high-interest balances and pay them off more quickly.
- Home Equity Loans or HELOCs: If you own a home, you may be able to borrow against your equity to consolidate debt. However, be cautious as your home is used as collateral.
Carefully consider the terms and fees associated with each option before making a decision.
5. Seek Credit Counseling
If you're struggling to manage your debt, consider seeking help from a reputable credit counseling agency. These agencies can provide financial education, budget counseling, and debt management plans. They can also negotiate with your creditors on your behalf to lower your interest rates and monthly payments. Make sure to choose a non-profit credit counseling agency that is accredited by the National Foundation for Credit Counseling (NFCC).
6. Avoid Taking on More Debt
This might seem obvious, but it's crucial to avoid taking on more debt while you're trying to manage your existing debt. Resist the urge to use credit cards for non-essential purchases. Focus on living within your means and saving for unexpected expenses. Building an emergency fund can help you avoid relying on credit when faced with unforeseen circumstances.
7. Monitor Your Credit Report Regularly
Regularly checking your credit report allows you to identify any errors or fraudulent activity that could negatively impact your credit score. You are entitled to a free credit report from each of the three major credit bureaus (Equifax, Experian, and TransUnion) once a year. Review your credit reports carefully and dispute any inaccuracies you find.
What to Do If a Debt Collector Contacts You
Even with the best planning, you may still be contacted by a debt collector. Here's how to handle the situation:
1. Request Debt Validation in Writing
As mentioned earlier, you have the right to request validation of the debt. Send a written request to the debt collector within 30 days of their initial contact. This request should include the account number, the amount of the debt, and a request for documentation proving that you owe the money. Keep a copy of your request for your records.
2. Don't Admit to the Debt
Even if you believe you owe the debt, avoid admitting to it until you have received validation. Admitting to the debt can restart the statute of limitations, which is the time limit within which a creditor can sue you to collect the debt. If the statute of limitations has expired, the debt is considered time-barred, and the creditor cannot legally sue you to collect it.
3. Communicate in Writing
Whenever possible, communicate with debt collectors in writing. This provides a clear record of your interactions and prevents misunderstandings. Keep copies of all correspondence for your records.
4. Know Your Limits
Understand your financial limitations and be realistic about what you can afford to pay. Don't agree to a payment plan that you cannot realistically maintain. It's better to be honest about your situation and negotiate a manageable payment plan than to default on an agreement and face further collection efforts.
5. Seek Legal Advice
If you are being harassed or threatened by a debt collector, or if you believe they are violating the FDCPA, seek legal advice from an attorney specializing in debt collection defense. An attorney can help you understand your rights and options and represent you in legal proceedings if necessary.

0 Comments