Understanding the Interplay of Insurance Risk and Credit Risk
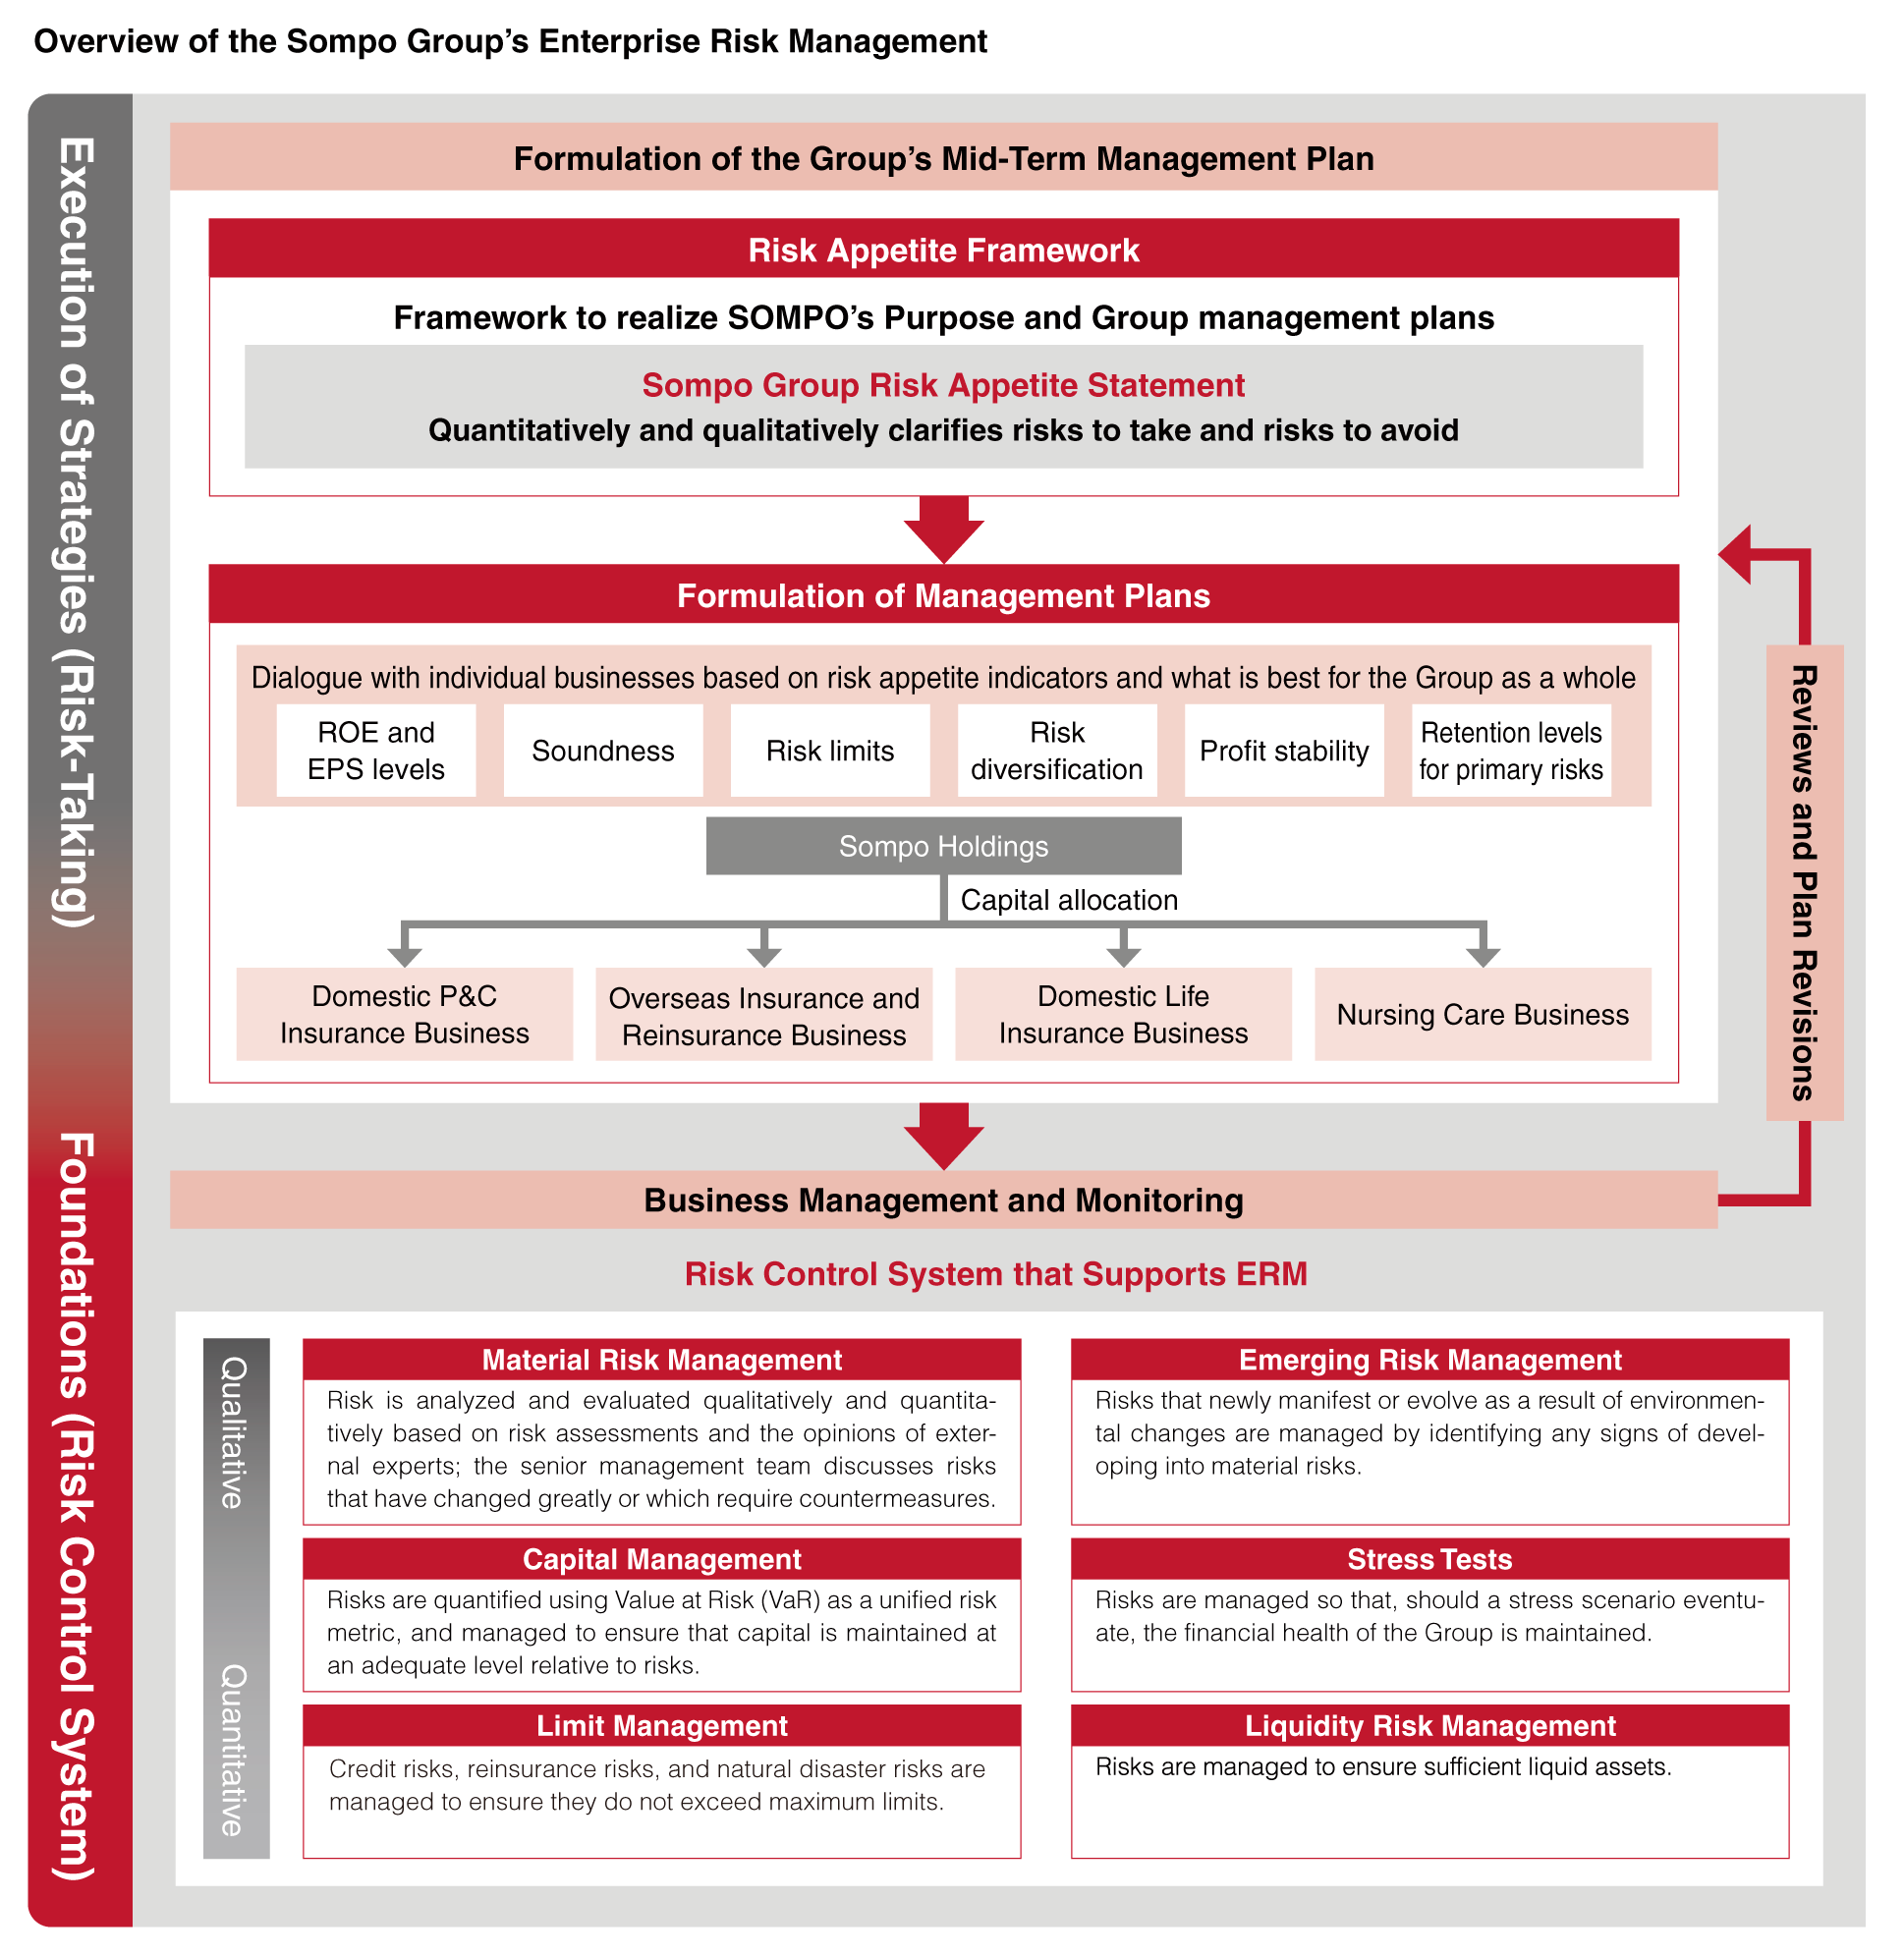
In the complex landscape of modern finance, understanding and mitigating risk is paramount. Two crucial areas of risk management are insurance risk management and credit risk management. While seemingly distinct, these areas often intersect and influence each other. Effective strategies in both are essential for maintaining financial stability and protecting assets.
Insurance risk management focuses on identifying, assessing, and mitigating risks associated with insurance policies. This includes risks related to underwriting, claims, and investments. Credit risk management, on the other hand, centers on evaluating and controlling the risk of loss resulting from a borrower's failure to repay a debt. Both fields employ various techniques and strategies to minimize potential losses and ensure the solvency of institutions.
Insurance Risk Management: A Deep Dive
Insurance companies face a multitude of risks, ranging from natural disasters to unexpected health crises. Effective insurance risk management involves a holistic approach that encompasses various aspects of the insurance business.
Key Components of Insurance Risk Management
Several key components contribute to a robust insurance risk management framework:
- Risk Identification: Identifying potential risks that could impact the insurance company's operations and financial performance. This includes underwriting risk, operational risk, market risk, and credit risk (yes, insurance companies also face credit risk!).
- Risk Assessment: Evaluating the likelihood and potential impact of each identified risk. This often involves using statistical models and actuarial analysis to quantify the potential losses.
- Risk Mitigation: Developing and implementing strategies to reduce the likelihood or impact of identified risks. This could involve reinsurance, diversification of insurance portfolios, and implementing stricter underwriting guidelines.
- Risk Monitoring and Reporting: Continuously monitoring the effectiveness of risk mitigation strategies and reporting on the company's overall risk profile. This allows for timely adjustments and improvements to the risk management framework.
Strategies for Mitigating Insurance Risk
Insurance companies employ various strategies to mitigate the risks they face:
- Reinsurance: Transferring a portion of the risk to another insurance company (the reinsurer) in exchange for a premium. This helps to reduce the potential for large losses from catastrophic events.
- Underwriting Guidelines: Implementing strict underwriting guidelines to ensure that policies are only issued to individuals or entities that meet certain criteria. This helps to reduce the likelihood of claims.
- Diversification: Diversifying the insurance portfolio across different types of policies and geographic regions. This helps to reduce the concentration of risk in any one area.
- Pricing and Reserving: Accurately pricing insurance policies and establishing adequate reserves to cover potential claims. This ensures that the company has sufficient funds to meet its obligations.
Credit Risk Management: Protecting Against Default
Credit risk management is a critical function for banks, lending institutions, and any organization that extends credit to customers. It involves assessing the creditworthiness of borrowers and implementing strategies to minimize the risk of default.
Key Components of Credit Risk Management
A comprehensive credit risk management framework includes the following key components:
- Credit Risk Assessment: Evaluating the creditworthiness of potential borrowers based on their financial history, credit score, and other relevant factors.
- Credit Scoring Models: Using statistical models to predict the likelihood of default based on various factors.
- Credit Limits: Establishing appropriate credit limits for borrowers based on their creditworthiness.
- Collateralization: Requiring borrowers to provide collateral to secure the loan. This provides the lender with recourse in the event of default.
- Monitoring and Reporting: Continuously monitoring the credit performance of borrowers and reporting on the overall credit risk profile of the lending portfolio.
Strategies for Mitigating Credit Risk
Various strategies can be employed to mitigate credit risk:
- Credit Insurance: Purchasing credit insurance to protect against losses from borrower default. This is particularly useful for businesses that extend credit to customers.
- Diversification: Diversifying the loan portfolio across different industries and geographic regions. This helps to reduce the concentration of risk in any one area.
- Loan Covenants: Including loan covenants in loan agreements to protect the lender's interests. These covenants may require the borrower to maintain certain financial ratios or restrict their ability to take on additional debt.
- Securitization: Pooling together a portfolio of loans and selling them to investors as securities. This helps to diversify the lender's risk and free up capital for new lending.
- Early Warning Systems: Implementing early warning systems to identify borrowers who are at risk of default. This allows the lender to take proactive steps to mitigate the risk.
The Intersection of Insurance Risk and Credit Risk
While insurance risk management and credit risk management are distinct disciplines, they are often interconnected. For example, insurance companies may face credit risk when investing in bonds or lending to other institutions. Similarly, lenders may require borrowers to purchase insurance to protect against certain risks, such as property damage or business interruption.
Furthermore, the economic environment can impact both insurance risk and credit risk. For example, a recession can lead to increased defaults on loans and increased claims under unemployment insurance policies. Therefore, it is important for financial institutions to consider the interplay of these risks when developing their risk management strategies.
Managing Overlapping Risks
To effectively manage overlapping insurance risk and credit risk, organizations should:
- Implement a holistic risk management framework: This framework should integrate both insurance risk and credit risk management processes.
- Share information across departments: Insurance and credit risk management teams should share information and insights to identify potential overlaps and correlations between risks.
- Develop stress testing scenarios: Stress testing scenarios should consider the impact of adverse events on both insurance and credit risk exposures.
- Establish clear lines of responsibility: Clearly define the roles and responsibilities of individuals and departments involved in managing insurance risk and credit risk.
The Role of Technology in Risk Management
Technology plays an increasingly important role in both insurance risk management and credit risk management. Advanced analytics, machine learning, and artificial intelligence are being used to improve risk assessment, pricing, and monitoring.
Technological Advancements in Insurance Risk Management
Insurance companies are leveraging technology in various ways:
- Predictive Modeling: Using predictive modeling to forecast claims frequency and severity.
- Fraud Detection: Employing machine learning algorithms to detect fraudulent claims.
- Automated Underwriting: Automating the underwriting process to improve efficiency and accuracy.
- Real-Time Monitoring: Monitoring risk exposures in real-time using data analytics dashboards.
Technological Advancements in Credit Risk Management
Similarly, technology is transforming credit risk management:
- Credit Scoring Algorithms: Developing more sophisticated credit scoring algorithms using machine learning.
- Alternative Data Sources: Incorporating alternative data sources, such as social media data, into credit risk assessments.
- Automated Loan Origination: Automating the loan origination process to improve efficiency and reduce costs.
- Early Warning Systems: Developing more sophisticated early warning systems to identify borrowers at risk of default.
By embracing technology, organizations can enhance their risk management capabilities and improve their overall financial performance.

0 Comments