
Understanding Real Estate Investment Financing
Real estate investment offers numerous potential benefits, including passive income, appreciation, and tax advantages. However, securing the necessary financing can be a significant hurdle for many aspiring investors. Understanding the various investment strategies for financing real estate is crucial for maximizing returns and minimizing risks. This article explores several popular and effective financing methods to help you navigate the real estate investment landscape.
Traditional Mortgage Financing
The most common method of financing real estate investments is through traditional mortgages. These loans are typically offered by banks, credit unions, and other financial institutions and are secured by the property itself.
Conventional Mortgages
Conventional mortgages are not insured or guaranteed by the government. They usually require a higher down payment (typically 20% or more) and a good credit score. While they may have stricter requirements, conventional mortgages often come with lower interest rates compared to government-backed loans.
FHA Loans
Federal Housing Administration (FHA) loans are insured by the government, making them more accessible to borrowers with lower credit scores and smaller down payments (as low as 3.5%). FHA loans often have stricter requirements regarding the property's condition and may require mortgage insurance premiums (MIP) for the life of the loan.
VA Loans
VA loans are guaranteed by the Department of Veterans Affairs and are available to eligible veterans, active-duty service members, and surviving spouses. VA loans often have no down payment requirement and offer competitive interest rates. They also typically do not require private mortgage insurance (PMI).
Alternative Financing Options
While traditional mortgages are a popular choice, several alternative financing options can be particularly useful for real estate investors.
Hard Money Loans
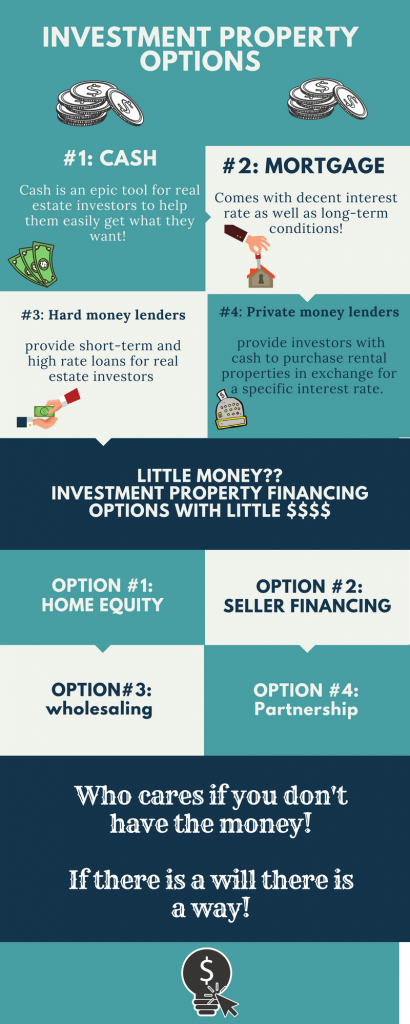
Hard money loans are short-term loans secured by real estate. They are typically offered by private lenders and are often used for fix-and-flip projects or other short-term investments. Hard money loans have higher interest rates and fees compared to traditional mortgages but can be a valuable option for investors who need quick access to capital.
Private Money Loans
Similar to hard money loans, private money loans are also sourced from private lenders, such as individuals or investment groups. The terms and conditions of private money loans are often negotiable, making them a flexible option for investors who need customized financing solutions.
Seller Financing
Seller financing, also known as owner financing, involves the seller of the property acting as the lender. The buyer makes payments directly to the seller according to the agreed-upon terms. Seller financing can be a great option for buyers who have difficulty qualifying for traditional mortgages or who are looking for more flexible financing arrangements. It can also benefit the seller by providing a steady stream of income and potential tax advantages.
Partnerships and Joint Ventures
Partnering with other investors or forming a joint venture can be an effective way to pool resources and share the financial burden of a real estate investment. This can be particularly useful for larger projects or for investors who lack sufficient capital on their own. Partnerships and joint ventures require careful planning and clear agreements to ensure that all parties are aligned and protected.
Creative Financing Strategies
Beyond the more common financing methods, several creative strategies can help investors acquire real estate.
Lease Options
A lease option gives the tenant the right, but not the obligation, to purchase the property at a predetermined price within a specified timeframe. Lease options can be a good way for investors to control a property with a relatively small upfront investment. They can also be attractive to potential buyers who need time to improve their credit score or save for a down payment.
Subject-To Financing
Subject-to financing involves purchasing a property "subject to" the existing mortgage. The buyer takes ownership of the property but does not assume the seller's mortgage. This can be a risky strategy for both the buyer and the seller, as the seller remains liable for the mortgage and the buyer's actions could impact the seller's credit. It's crucial to consult with legal and financial professionals before engaging in subject-to financing.
BRRRR Method (Buy, Rehab, Rent, Refinance, Repeat)
The BRRRR method is a popular strategy that involves buying a distressed property, rehabilitating it, renting it out, refinancing the property based on its new value, and then using the cash-out refinance to repeat the process with another property. This strategy allows investors to build their real estate portfolio quickly by leveraging the equity they create through renovations.
Securing Financing: Key Considerations
Regardless of the financing strategy you choose, several key considerations can increase your chances of securing the necessary funding.
Credit Score
A good credit score is essential for obtaining favorable loan terms. Lenders use credit scores to assess the risk of lending to a borrower. Improving your credit score can significantly reduce your interest rate and increase your borrowing power.
Debt-to-Income Ratio (DTI)
Your DTI is the percentage of your gross monthly income that goes towards debt payments. Lenders use DTI to assess your ability to repay the loan. A lower DTI indicates a lower risk for the lender.
Down Payment
The amount of down payment you provide can significantly impact your loan terms. A larger down payment reduces the lender's risk and can result in a lower interest rate and better loan terms.
Property Appraisal
Lenders will require a property appraisal to determine the fair market value of the property. The appraisal helps ensure that the loan amount is justified by the property's value.
Financial Documentation
Be prepared to provide lenders with comprehensive financial documentation, including tax returns, bank statements, and proof of income. This documentation helps lenders assess your financial stability and ability to repay the loan.

0 Comments